Deadline looms for Help to Buy (ISA)
 nova
5 November 2019
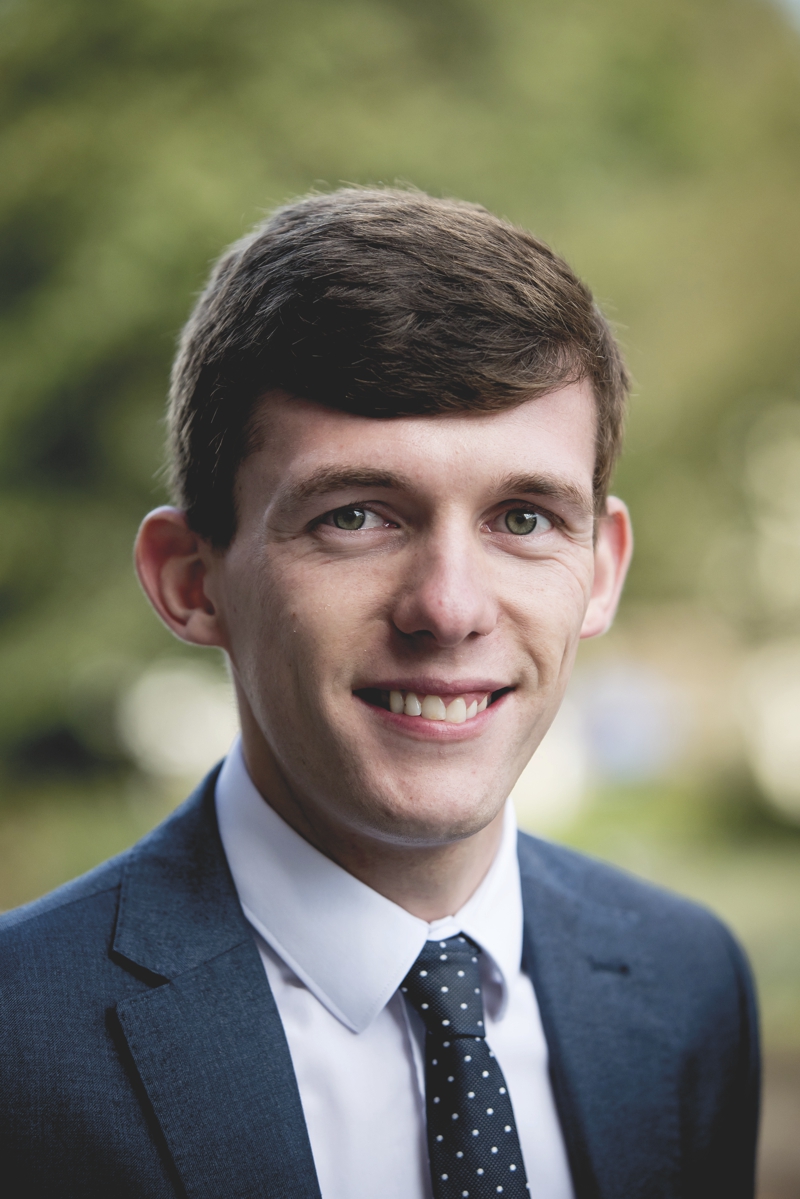
Stephen Graves, my director at Robert Nicholas Financial Advisers who usually writes in the NOVA Magazine, has passed this piece over to myself as I can relate from my past experience.
Ihave been at the company for four years, and at the start of this year, I became a fully qualified Independent Financial Adviser.
18 months ago, I purchased my first home after saving for many years whilst living with my parents. Although living with my parents had its many perks (washing, ironing, and cooking), there was no better feeling then being able to purchase my current home. I used the Help to Buy ISA which made regular saving more structured and, also, the 25% bonus at the end of the process eased some of the costs of purchasing my property.
However, time is running out to open the Help to Buy ISA! It will no longer be available to new savers from 30 November 2019. Individuals with existing accounts will still be able to save in this product but must claim the bonus by 1 December 2030.
What is the Help to Buy ISA?
It is a savings product designed to help first time buyers save up a deposit towards the purchase of their first home.
You can start your ISA with an opening deposit of up to £1,000 then carry on saving by contributing up to a maximum of £200 per calendar month. When you eventually close your account to purchase a house, the government will provide a bonus of 25%. The maximum bonus you can receive is £3,000, if you are able to save £12,000.
To qualify for the bonus
You must be a first-time buyer, aged 16 or over
You must save a minimum of £1,600 before you can claim the 25% bonus
The value of the property must be under £250,000 (or £450,000 in London)
It can be used with any mortgage i.e. you are not restricted to a Help to Buy mortgage
You cannot purchase a property oversees
An individual cannot have more than one Help to Buy ISA, although a couple buying together can have one each (to potentially achieve a bigger bonus!)
The interest rates currently available for a Help to Buy ISA are very competitive, for example a couple of providers currently offer a rate of 2.5%. Therefore, even if you do not eventually use the savings for a house purchase and miss out on the bonus, you will still benefit from an advantageous rate.
What if you miss the deadline?
The LISA (Lifetime ISA) was introduced in 2017 and is set to replace the Help to Buy ISA. It too offers a 25% government bonus; however, the rules are very different compared to the Help to Buy ISA.
If you want to discuss the best ways to help to save towards a mortgage, or the mortgage process itself, why not contact us? However, do not forget, you only have the option to open a Help to Buy ISA up to the 30 November!
Lee Taylor
Robert Nicholas Financial Advisers Ltd.






